


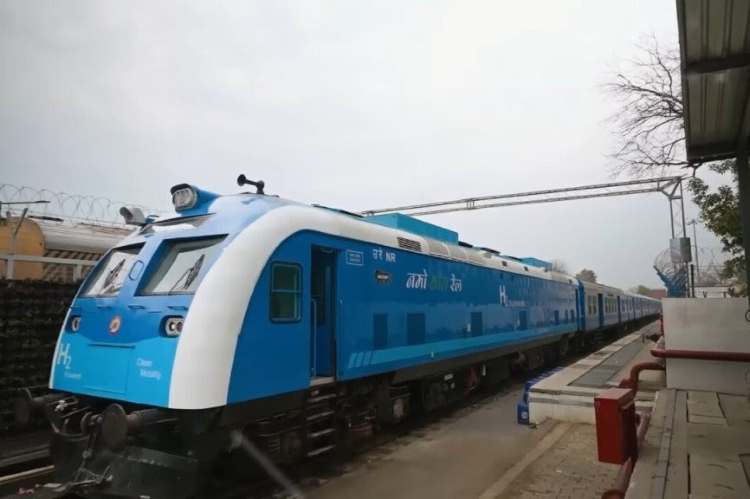
Green hydrogen could play a key role in India’s clean energy transition, particularly in sectors where direct electrification is difficult. Green hydrogen (GH) is produced by splitting water using renewable energy, while grey hydrogen is made from natural gas, releasing significant CO₂ emissions.
Green hydrogen can replace grey hydrogen in fertilisers and refineries, coal in steelmaking, and fossil fuels in parts of the chemicals, petrochemicals and heavy transport sectors, including shipping.
Besides reducing emissions, it can lower dependence on imported fossil fuels and industrial feedstocks, limit exposure to global price volatility and strengthen energy security. However, large-scale adoption will depend on costs, end-use efficiency and supporting infrastructure.
READ I Renewable energy transition faces grid and pricing risks
National Green Hydrogen Mission
Recognising Green Hydrogen as a strategic energy carrier, the Government of India launched the National Green Hydrogen Mission (NGHM) in January 2023. The mission aims to make India a global hub for GH production, use and exports, with a target of at least 5 million tonnes (Mt) of annual production by 2030.
By December 2025, the government had awarded incentives for 0.862 million tonnes per annum (MTPA) of production capacity and 3,000 MW per annum of electrolyser manufacturing. The awarded GH production capacity represents only about 17% of the 2030 target.
Cost remains a major barrier to large-scale GH adoption in the domestic market. The International Energy Agency (IEA) has also highlighted this challenge. Its recent report says uncertain demand and project delays, partly due to slow infrastructure development, mean GH is unlikely to become cheaper than grey alternatives in the near future.
To address costs, NGHM provides short-term subsidies and policy support to incentivise production. It has also identified three ports — Deendayal, V.O. Chidambaranar and Paradip — as GH hubs to coordinate production, storage, handling and shipping for potential exports.
Under NGHM, Rs. 174,900 million has been allocated to the Strategic Interventions for Green Hydrogen Transition (SIGHT) programme. Declining production subsidies on GH (Rs. 50 to Rs. 30 per kg) and green ammonia (Rs. 8.8 to Rs. 5.3 per kg) are available for only three years. They cover only 10-15% of the green-grey cost gap and are intended as a temporary incentive. Electrolyser manufacturing incentives are spread over five years, declining from Rs. 4,440 to Rs. 1,480 per kW.
Long-term sustainability will require measures beyond subsidies. These include creating demand in hydrogen-consuming industries through a Green Hydrogen Production Obligation; reducing production costs through cheaper RE and domestic electrolyser manufacturing, supported by performance-linked incentives; and developing export markets along with carbon pricing for grey hydrogen
RE is a major cost component (50–70% of green hydrogen production costs), particularly when round-the-clock supply is required. To lower production costs, encourage domestic adoption and strengthen India’s export competitiveness, the government has notified the waiver of Inter-State Transmission System (ISTS) charges for eligible GH and green ammonia projects.
Green hydrogen trade
According to WITS data, India imported hydrogen worth $871,700 in 2024, while exports amounted to $17,400. Nigeria was the largest destination for Indian hydrogen exports (45.8%), followed by Nepal, Bangladesh, Bhutan and Sri Lanka.
India has considerable scope to expand its export network. Current estimates suggest that the European Union and East Asia could together import around 3.4-6 million tonnes of GH annually by 2030. However, these figures understate the emerging GH market, because they do not distinguish hydrogen by electricity source or include trade in derivatives.
In July 2026, ACME Group (0.4 MTPA under NGHM) signed long-term supply agreements with Japan from its Paradip facility — 0.41 MTPA green ammonia for IHI and 1.0 MTPA green methanol for Mitsubishi Gas Chemical.
India has also pursued hydrogen cooperation and export-infrastructure partnerships with Germany and other countries.
Challenges to green hydrogen plan
Despite India’s substantial RE potential, the economics of large-scale GH production will depend on land and water availability, and the cost of RE generation and electrolysers. Water-stressed locations will need credible sourcing and treatment plans, including desalination where necessary.
Dependence on global supply chains for electrolysers and RE equipment also leaves GH production exposed to concentrated manufacturing and critical mineral dependencies.
Another challenge is the distance between RE generation centres and designated GH hub ports. Kandla port, for instance, is relatively close to renewable-rich clusters in Gujarat and Rajasthan, while Paradip is considerably farther from such areas.
The distance between RE sources and GH production facilities is, therefore, a critical consideration. Hydrogen can be produced using RE wheeled from distant generation facilities through ISTS.
Transporting GH over long distances also poses economic challenges because of the high costs of compression (200-700 bar) or liquefaction (-253°C).
A potentially more viable option is to convert GH into derivatives at the source and transport them through existing infrastructure.
Decentralised use by nearby refineries and fertiliser plants, preferably through blended natural gas pipelines, with only surplus production exported as ammonia, could further avoid the cost of transporting pure hydrogen.
Exports of GH and its derivatives can earn foreign exchange, reduce fossil fuel import bills and help projects achieve economies of scale.
While the domestic market for these products is still emerging and price-sensitive, an export-oriented approach could lower production costs and prices, thereby stimulating domestic demand.
Export markets add their own conditions: EU buyers require EU rules for renewable fuels of non-biological origin (RFNBO) compliance, including proof of RE sourcing. Certification and traceability must therefore be built in from the outset, alongside product quality, safe port operations and reliable delivery.
Building a robust GH value chain will require prioritising competitive production routes, targeting low-hanging applications where hydrogen is already in use, and complementing policy and financial incentives with demand-creation measures.
India can become a regional and global supplier of green hydrogen and its derivatives, but exports must reinforce — not distract from — the domestic transition. Success will depend on competitive low-emissions production, replacing fossil-based inputs at home, securing reliable export buyers and delivering measurable emissions reductions.
Sanchit Agarwal is Fellow and Area Convenor at the Centre for Energy Assessment and Modelling area of The Energy and Resources Institute (TERI), New Delhi. Saswata Chaudhury is Senior Fellow, Centre for Energy Assessment and Modelling Division, The Energy and Resources Institute, New Delhi. Originally published under Creative Commons by 360info .