


India’s tree finance must go beyond plantations: India has excelled in setting tree-planting targets. The Green India Mission, CAMPA, agroforestry programmes, urban forestry and state plantation campaigns have put substantial public resources behind expanding tree cover. Yet plantation policy still has a basic weakness: it is better at financing the act of planting than the outcome of growing trees.
That distinction has come under scrutiny again after two developments in August 2026. The government told Parliament that the Green India Mission had brought 1,84,467 hectares under eco-restoration in 17 states and one Union territory since 2015-16. On August 12, the Comptroller and Auditor General tabled a performance audit of the mission.
READ | Forest finance must measure its social costs
The Green India Mission was designed to improve the quality and extent of forest and non-forest landscapes across 10 million hectares. The latest figures show how much remains to be done. They also raise a question that applies beyond this particular programme: what happens to public investment after the sapling has been planted?
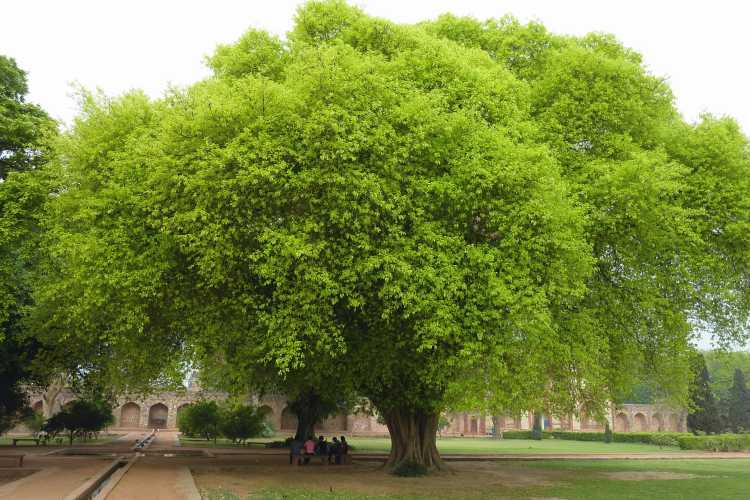
A sapling does not become a carbon sink, timber asset, biodiversity gain or source of rural income simply because it has been planted. Its value depends on survival, growth, species suitability and continued management. Public programmes therefore need to measure what happens to trees after plantation, not merely whether plantation targets were met.
From plantation targets to tree performance
This is where India’s plantation economics needs to change.
The CAG’s 2024 performance audit of afforestation and social forestry in Uttar Pradesh examined plantation planning and execution as well as monitoring, evaluation and internal controls. The audit covered 2016-17 to 2021-22. Its findings reinforce a broader point about public plantation spending: verification cannot end when planting is completed.
The relevant measures should include survival after one year, stocking and growth after three years, and the condition and use of the plantation after five years. Species selection and site suitability also need to be assessed. For agroforestry, the economic test must extend to whether farmers can eventually sell the timber or other products generated by their trees.
Such measurements would change what governments pay for. A portion of public and blended finance could be released against independently verified performance instead of being tied mainly to the completion of plantation work.
An initial payment could cover site preparation and planting. Later payments could depend on survival and growth. A five-year milestone could assess ecological performance, continued management and, where relevant, income generated for farmers or communities. Upfront support would remain necessary because trees require several years to mature. The difference would be that part of the financial risk would remain linked to the condition of the trees.
That matters because a plantation programme can meet its planting target even when a significant proportion of the trees subsequently die or fail to grow as intended. The public expenditure is recorded, but the ecological or economic asset expected from it may never materialise.
READ | India’s carbon market needs a firewall
India already has the foundations of a tree economy
The economic case for changing this approach is substantial. The India State of Forest Report 2023 estimates growing stock outside forests at 1,951 million cubic metres and annual potential production of industrial wood from trees outside forests at 91.51 million cubic metres. Trees outside forests include trees on farms and other non-forest land, making them an important source of future timber supply.
Agroforestry is already widespread. NITI Aayog estimates that it covers about 28.42 million hectares, or 8.65% of India’s geographical area.
These figures describe an economic activity that extends well beyond government plantation schemes. Farmers grow trees, nurseries supply planting material, aggregators bring produce to market, processors convert it into usable products and buyers create demand. Each part of this chain affects the returns available to the farmer who carries the cost of waiting for a tree to mature.
That chain remains weak in several places. Farmers can struggle to obtain quality planting material and finance long-rotation crops. Timber markets can be uncertain, processing capacity may be far from production areas, and insurance products for trees remain limited. Regulatory restrictions on harvesting and transporting some tree species can also affect the economics of farm forestry.
The government has begun addressing one part of the problem. The former Sub-Mission on Agroforestry was restructured as the Agroforestry Component under PM-RKVY from 2023-24. The programme supports new nurseries, sapling production, tissue-culture units, research and monitoring, among other activities intended to improve access to quality planting material.
The next step is to connect such interventions. A farmer who receives a better sapling but cannot obtain finance, protect the crop from risk or find a buyer still has a weak business proposition.
READ | Delhi urban heat island exposes planning neglect
Finance should follow the tree
Performance-linked plantation finance could help close that gap.
Banks could lend to professionally managed agroforestry portfolios if reliable information made future tree stocks and expected cash flows easier to assess. Insurers could develop products covering fire, drought and extreme weather where the risks can be priced. Corporate social responsibility funding could support restoration projects against independently verified outcomes. Carbon finance could supplement revenues where projects meet credible requirements for additionality, permanence and measurement.
Digital monitoring makes parts of this system more feasible than they were in the past. Satellite imagery, GIS, drones and geotagged field observations can establish whether plantations remain in place and how they are developing. They cannot eliminate the need for field verification, particularly where survival rates, species condition or community benefits determine payments. But they can make monitoring more frequent and less dependent on occasional physical inspections.
Better information could also reduce some of the uncertainty faced by lenders and insurers. A bank considering an agroforestry portfolio needs to know whether the trees are still standing and developing as projected. An insurer needs evidence on the condition and location of the insured asset. A timber buyer needs better information about future supply. The same underlying data can serve all three purposes.
There is, however, a boundary that plantation finance should not cross. Commercial tree planting cannot become a justification for replacing natural forests, grasslands or wetlands with plantations. These ecosystems provide ecological functions that cannot be reduced to timber production or carbon storage.
The commercial opportunity is therefore strongest in agroforestry, trees outside forests and suitable degraded lands where tree production is compatible with local ecological conditions and land rights.
That requires safeguards at the project level. Land tenure or farmer consent should be established before finance is committed. Species should be appropriate to the site. Projects should demonstrate that natural ecosystems will not be cleared to make way for plantations. Maintenance arrangements should be credible, and projects involving communities should specify how benefits will be shared.
For commercial agroforestry, access to buyers and processing facilities should also be considered before trees are planted. A tree that survives but cannot reach a viable market is an ecological success in some circumstances, but it may not provide the income that justified the investment.
Tree finance: Measure what survives
India does not necessarily need another tree-planting target. It needs better returns from the programmes already in place.
The Green India Mission’s 1,84,467 hectares of eco-restoration since 2015-16 is an important measure of activity, but it does not by itself establish the condition of those landscapes today. The same limitation applies to plantation numbers reported under other programmes. A hectare planted and a hectare of established, healthy trees are different assets.
The next phase of plantation policy should therefore give greater weight to what happens after planting. Survival, growth, ecological condition and, where relevant, farmer income should become part of the measurement system used to determine whether public money has achieved its intended purpose.
This would also change the economics for the private sector. Nurseries would have stronger incentives to supply reliable planting material. Growers would have a clearer basis for obtaining finance. Insurers and lenders would have better information on which to price risk. Processors and buyers could plan around more reliable future supply.
India has spent years building programmes that put trees into the ground. The more difficult task is to keep those trees alive, allow them to grow, and create the conditions under which farmers and communities can earn from them. Plantation policy will become more effective when public money follows that longer process rather than treating planting as the end of it.
The writer is Senior Associate Fellow, Land Resources Division, The Energy and Resources Institute (TERI), New Delhi.