


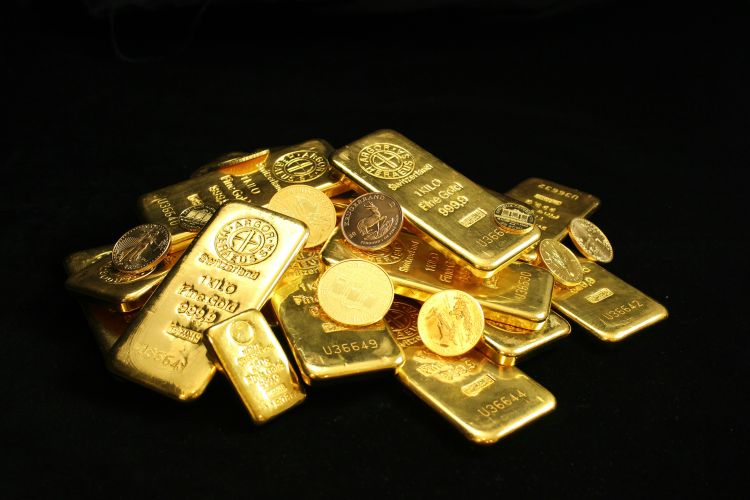
World gold prices: Gold has had a sharp correction from its January peak, but the forces behind its long rise have not gone away. On September 22, spot gold was around $4,342 an ounce, after the Federal Reserve’s rate increase and renewed expectations of higher US yields put pressure on the metal. Yet the important question for gold is no longer simply where US interest rates are headed. Central banks are buying bullion for reasons that have little to do with the next Fed meeting, while wars, sanctions and concerns over the durability of the dollar-based financial system are giving governments and investors reasons to diversify.
Gold now has buyers whose decisions are less sensitive to the US interest-rate cycle. Central banks are accumulating bullion as a reserve asset, Asian investors are taking a larger role in price formation, and geopolitical fragmentation is making diversification a policy objective. The result is unlikely to be a one-way rise. It is more likely to be a market of sharp corrections around a higher floor.
READ | India’s gold demand is a hedge, not a weakness
Gold traded above $5,500 an ounce in January before falling below $4,000 in June. The lesson is that gold can fall substantially when yields rise, the dollar strengthens and investors take profits. What has changed is the depth of demand underneath the market.
Central banks are becoming structural buyers
The old relationship between gold and interest rates still matters. Gold pays no interest, so higher real yields make Treasury securities and cash more attractive. A strong dollar raises the cost of bullion for buyers using other currencies. This explains why gold can fall sharply even during a broader bull market. But they no longer tell the whole story. The rise of official-sector demand has given gold a second engine, one that is driven less by short-term monetary policy than by how central banks assess currency, sanctions and geopolitical risk.
China is particularly important. The People’s Bank of China bought 20.2 tonnes in August, its largest monthly addition since October 2023, taking official holdings to 2,387 tonnes. It has now reported purchases for 22 consecutive months. Chinese gold ETFs added 11 tonnes in August and continued to attract inflows in early September.
This is more than a response to the latest price. Reserve managers are reassessing concentration risk. The freezing of Russia’s foreign-exchange reserves in 2022 demonstrated that financial assets held abroad can become subject to sanctions. Gold is less liquid than US Treasuries, but it carries no sovereign issuer’s credit risk.
The IMF has described the renewed importance of gold in central-bank reserves while cautioning that some of the increase in gold’s share reflects higher prices rather than a comparable increase in physical holdings. That qualification matters. It does not erase the change in reserve-management behaviour.
Diversification is giving gold a second source of demand
The dollar remains dominant. There is no credible near-term substitute for the depth and liquidity of US financial markets. But dependence on one reserve currency is increasingly viewed as a risk.
An IMF analysis published in September says Asian economies are developing alternative channels for trade and finance as geopolitical fragmentation grows. The Bank for International Settlements has likewise noted that sanctions, settlement access and geopolitical concentration are becoming part of reserve-management decisions.
READ | Gold imports, oil prices expose limits of austerity calls
Gold fits this adjustment. It is not another currency competing to replace the dollar. It is an asset outside the liability structure of another government. That makes it useful insurance in a fragmented financial system.
China also shows why the old relationship between gold and US yields is becoming less reliable. Chinese demand is influenced by domestic bond yields, equity performance, the yuan and alternative investments. In August, Chinese gold ETFs expanded their holdings even as jewellery demand weakened. High prices are changing the composition of demand rather than eliminating it.
Supply cannot respond quickly
There is another reason for a higher price floor: supply is not very responsive to price.
World Gold Council data show mine production rose 2% year-on-year in the second quarter to 966 tonnes, a record for a second quarter. But total supply was almost unchanged because recycling fell 6%. New mines take years to develop, while existing mines face geological, environmental and regulatory constraints.
The market is also being supported by over-the-counter demand, particularly in Asia. Total first-half gold demand, including OTC transactions, reached 2,522 tonnes, 2% higher than a year earlier. The value of that demand was a record $380 billion because prices were much higher.
War and oil keep the inflation hedge relevant
Geopolitics provides another support, but its effect is more complicated than a conventional safe-haven story.
The war involving Iran, Israel and the United States has disrupted energy markets and kept the Strait of Hormuz under pressure. Renewed fighting involving the Houthis in Yemen has added risks around the Bab el-Mandeb route. Brent crude was again above $100 a barrel on September 22 as markets waited for possible US-Iran talks.
The economic consequence is an awkward combination: higher energy prices can lift inflation while weaker confidence threatens growth. The IMF’s July outlook put global growth at 3% for 2026 and 3.4% for 2027, while warning that disinflation had stalled. Its recent assessment also highlighted the energy shock, high public debt and geopolitical uncertainty.
READ | Gold prices are telling something central banks will not say aloud
The Fed is the main brake
There is a powerful counterargument. The Federal Reserve has just raised rates to 3.75%-4%, and inflation remains above its 2% goal. Higher real yields and a stronger dollar can pull capital towards interest-bearing assets and away from gold.
That is already visible. World Gold Council data show gold ETFs lost 45 tonnes in the second quarter. The Council expects Western ETF flows to remain sensitive to yields, monetary policy expectations and the dollar. If US growth remains strong while inflation stays high, the Fed could keep rates restrictive for longer.
But the Fed does not control all demand. A central bank in Asia buying bullion for reserve diversification is responding to different risks from a US asset manager choosing between gold and Treasury bills. The market has acquired multiple sources of demand.
The better question is therefore not whether gold will rise every month. It will not. The question is whether the forces supporting a higher long-term price are stronger than those that produced the previous cycle’s corrections.
J.P. Morgan Global Research expects gold to average $6,000 an ounce in the fourth quarter and move towards $6,300 by the end of 2027. The World Gold Council is more cautious, saying gold could remain range-bound if growth stays resilient and yields rise. Neither is a certainty.
If geopolitical tensions ease, oil falls and US real yields rise, gold can correct sharply. If reserve diversification continues, energy risks persist and confidence in the international monetary system weakens, buyers are likely to return at lower prices.
That is the central change in the market. Gold no longer needs a crisis every time it rises. A more fragmented world economy has created a permanent constituency for bullion. The next rally may be interrupted, but the forces capable of restarting it are becoming harder to remove.