


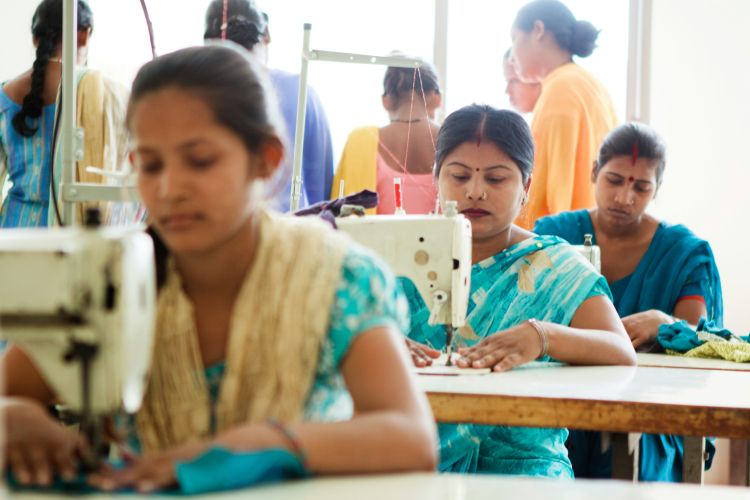
Skill development: India’s skilling apparatus is getting better at counting people. It is far less certain that it knows what happens to them after the course ends.
The Ministry of MSME’s dashboard shows that PM Vishwakarma had reached 3 million registrations by July 31, 2026, with about 2.43 million beneficiaries completing basic training. The Entrepreneurship and Skill Development Programme has also trained more than 2.2 million people. These are substantial numbers. They do not tell policymakers whether training raised earnings, helped a business survive, improved access to formal credit or gave an entrepreneur a more secure livelihood.
READ | Why skill development will decide India’s economic future
That measurement gap matters because substantial public and private money is going into development programmes. CRISIL Foundation estimates that qualifying listed companies spent more than ₹1.22 lakh crore on corporate social responsibility between FY2014 and FY2024. Education and skill development together received the largest share, at 18%. For companies funding livelihood programmes, counting people trained is therefore an inadequate measure of what their money achieved.
Development economist Naila Kabeer’s framework, developed to examine women’s empowerment, offers a useful way of thinking about the problem. It distinguishes between resources, agency and achievements. Access to training or finance is a resource. The ability to use it productively reflects agency. Higher and more secure earnings, business survival or greater economic independence are achievements. Measuring only the first tells us little about the other two.
Skill development: Measure livelihoods after the course ends
Monitoring and evaluation of skilling programmes should begin with the livelihood rather than the training centre.
For a micro-entrepreneur, relevant measures could include changes in business income, savings, formal borrowing and repayment behaviour. Business continuity six or twelve months after training is another useful indicator. So is the adoption of digital payments or bookkeeping when these are relevant to the enterprise.
READ | India’s skills vs degrees debate misses the real problem
No single measure is conclusive. Higher bank inflows do not necessarily mean higher income. Borrowing may indicate expansion or financial distress. Digital transactions can rise because customers change their payment habits rather than because the business is doing better. Measurement therefore requires a combination of indicators and a baseline against which subsequent changes can be assessed.
Structured surveys remain indispensable. They can establish the beneficiary’s circumstances before an intervention and examine what changed afterwards. They can also capture information that administrative or financial data cannot: control over household income, confidence in dealing with suppliers, working conditions or constraints faced by women entrepreneurs.
Surveys, however, are expensive when programmes cover large and dispersed populations. They are conducted periodically, and responses on income or past transactions can suffer from recall errors. Digital information can help fill some of these gaps.
Digital data can improve monitoring, with limits
A consent-based programme application could generate regular information relevant to an intervention. A digital bookkeeping tool, for instance, could record sales or inventory with the entrepreneur’s permission. Programme managers could track use of services offered through the application. Payment and financial records may provide additional evidence where they can be accessed lawfully.
The distinction between useful measurement and surveillance must be explicit.
Blanket access to transaction messages, applications installed on a phone or continuous location data would be difficult to justify merely because it makes monitoring easier. Geolocation, in particular, is a poor proxy for business expansion in many occupations and carries obvious privacy costs.
Any such system should be designed around the Digital Personal Data Protection Act, 2023 and the Digital Personal Data Protection Rules, 2025. Beneficiaries need to know what information is being collected, the purpose for which it will be used and how long it will be retained. Security and withdrawal of consent cannot be treated as technical details added later. The statutory framework is being implemented in phases, but programmes being designed now should anticipate its requirements.
There is also a question of proportionality. A programme seeking to find out whether a tailoring enterprise remains operational after a year does not need permanent access to the entrepreneur’s phone. Better monitoring should mean collecting better evidence, not collecting every piece of data that technology makes available.
READ | Why engineering education must focus on coding skills
Account Aggregator offers a model, not immediate access
India’s Account Aggregator system presents a more structured possibility for financial information. It allows customers to authorise the sharing of specified financial information held by regulated Financial Information Providers with eligible Financial Information Users.
This could eventually be valuable for livelihood evaluation. Financial records can provide evidence on cash flows, balances, borrowing and repayments without depending entirely on beneficiary recall.
There is, however, an important regulatory constraint. Under the present framework, a Financial Information User must be an entity registered with and regulated by a financial-sector regulator. An ordinary NGO implementing a skilling programme does not meet that definition. NGOs therefore cannot simply plug into the Account Aggregator network to obtain beneficiary financial data.
Extending such access to development programmes would require a regulatory decision and safeguards governing purpose, consent, retention and onward use of information. An alternative would be to borrow the principles underlying the Account Aggregator architecture without extending the network itself: narrowly defined requests, explicit consent, auditable access and the ability to revoke permission.
That is a more credible route than treating digital public infrastructure as a reservoir of data available for any socially desirable purpose.
AI should flag problems, not judge beneficiaries
Machine learning can help once programmes begin generating information at scale. Beneficiaries can be grouped by occupation, region, enterprise maturity and other relevant characteristics. Changes in business activity can then be compared with appropriate baselines.
Such systems may help identify enterprises that appear to be struggling. A sustained fall in activity, for example, could prompt a field officer to check whether the entrepreneur needs mentoring, market access or help obtaining finance. It could also alert programme managers when outcomes in one district consistently lag those elsewhere.
The temptation will be to go further and predict business survival, creditworthiness or future income for individual beneficiaries. That requires much greater caution.
A business can pause because demand is seasonal. Women may show different transaction patterns because household and enterprise finances overlap. Sparse digital records can make successful cash-based enterprises appear inactive. An algorithm trained on such data can convert these gaps into apparently objective judgments.
AI is therefore better used as an early-warning device for programme managers than as an automated arbiter of benefits, credit or programme success.
For CSR funders, this would still represent a major improvement. They could move beyond reporting how many people attended training and examine whether enterprises remained active, whether financial access improved and where interventions repeatedly failed. NGOs could identify beneficiaries who require follow-up instead of waiting for the next evaluation cycle.
India has invested heavily in the infrastructure for identity, payments and consent-based data sharing. Its skilling system now needs a less glamorous piece of infrastructure: credible evidence about what happens to people after training ends.
The value of such a system will not lie in producing more elaborate dashboards. It will lie in helping governments and CSR funders stop financing weak interventions, improve programmes that work and reach entrepreneurs before a temporary setback becomes business failure. The real test of a skilling programme begins when the training is over.
Ashish Desai is Associate Professor, Information Management and Analytics, and Samarpita Debnath, PGP 2025 student at S.P. Jain Institute of Management & Research (SPJIMR).